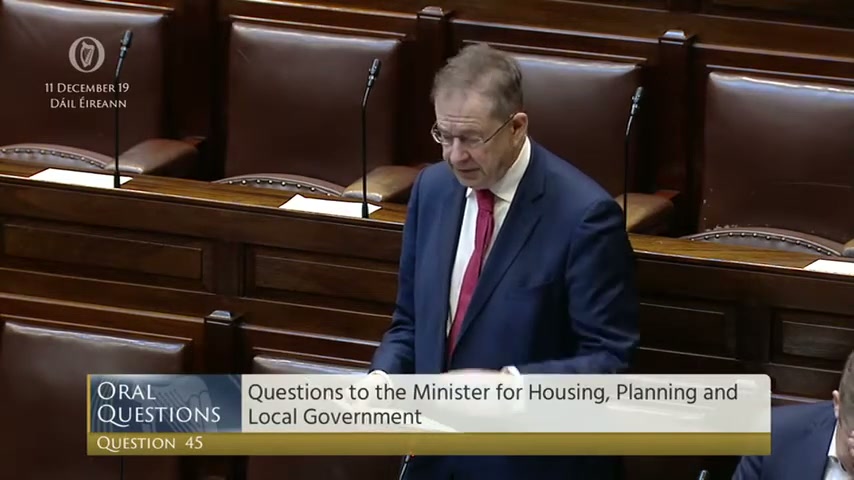
Éamon Ó Cuív challenges €15,000 rule in tenant purchase scheme
Éamon Ó Cuív pressed the minister on the tenant purchase scheme's €15,000 minimum income rule and its effect on tenants, particularly those on state pensions. He argued the income test can exclude pensioners who could afford to buy and raised questions about long-term maintenance obligations and application outcomes.
Question on sales and uptake
He asked how many houses have been sold under the scheme since its inception in 2016 and highlighted frequent queries from tenants who cannot access the scheme despite having funds to purchase upfront.
Income threshold and pension exclusion
He noted the scheme sets a minimum income of €15,000 as determined by local authorities under the Minister's Directions and queried a clause that excludes applicants if most of that income comes from social welfare, including state pension contributory payments. He said this provision can effectively bar couples on pensions from eligibility even when they could afford the property.
How reckonable income is calculated
The minister explained that local authorities may include income from employment, private pensions, maintenance payments and certain social welfare payments where employment income is primary. The incomes of all adult tenants and partners in the household are reckonable, while some payments - such as child benefit, carers allowance and the family working payment - are disregarded because they are not deemed long-term.
Rationale for the rule and maintenance concern
The minister defended the rule as intended to ensure long-term, sustainable income so new owner-occupiers can maintain the property, keep it in good repair, hold house insurance and meet obligations during the incremental purchase charge. The history of tenant purchase schemes showed cases where purchasers could not afford ongoing maintenance, prompting the income safeguard.
Scale of the issue and review plans
The minister said that in a sample year there were about 2,400 applications and less than a quarter were refused on eligibility grounds, so the income rule affects individual cases but is not the main reason for low uptake. He confirmed the matter is under review and that a forthcoming social housing package will address recommendations and seek ways to accommodate exceptional cases raised by deputies.
We publish thousands of recordings to make Irish politics transparent and resistant to manipulation. Spotted an error? Report it — together we are building a reliable archive of Irish politics.
Minister, you say it suits many people. Can you tell us how many houses have been sold since the inception of this scheme in 2016 to tenants under this scheme? And secondly, can you confirm that there is a requirement for £15,000 of an income, which is fair enough, but that there is a little quibble clause in there that says that if most of that is made up of a social welfare payment, even if it is a permanent social welfare payment such as a state pension contributory, that that is not taken into account and you cannot be eligible for the scheme. And that that effectively excludes a lot of people who are on state pensions who are the tenants of the house from availing of the scheme, even though they are likely to have saved money over a lifetime and be well able to afford the house. Again, just to deal with the income, yes, I can confirm there is an income limit that has to be €15,000 and that is the income that is set there at the moment. The minimum income eligibility under the 16 scheme is determined by the relevant local authority in accordance with the detailed provisions of the Minister's Directions, which includes that €15,000. In the determination of the minimum reasonable income, local authorities can include income from a number of different sources and classes, such as from employment, private pensions, maintenance payments and certain social welfare payments, including pensions where a social welfare payment is secondary to employment income. In the terming and reckonable income, the income of all tenants of the house, including adult children that are giant tenants, are named and are part of paying rent, is included, as is the income of the spouse, civil partner or other partner equivalent of a tenant who lives in the house with them, thus ensuring the appropriate level of discount is applied. Again, a number of income sources, including certain social welfare payments, are disregarded for the purposes of the terming and reckonable income. The list of income disregards includes child benefit, carers allowance and the family working payment, formerly family income supplement, as these are deemed not to be long term in nature. So they have to be in the long term of nature, but also the reason that is there, and it is one of the main issues of the review, and we have had this conversation and we are trying to find ways to accommodate cases that Deputy Sullivan brought forward, and others have brought forward from all parties as well, around that £15,000. I am glad that you have clarified that in the case of, for example, a couple on a state pension contributory, or maybe on two state pensions contributory, that if their other income is secondary to that, then they are excluded from the scheme, even if they can pay up front. I think we need to nail that here today, because that is one of the most common queries we are getting all the time in relation to this scheme, or other people who might, one way or another, have the money got to pay and buy the house. Now the excuse given, or the logic given for the rule, and can you confirm this, is that if they bought the house, people like that could not afford to maintain the house. Could you confirm, because that is the reason I have been given in writing, could you confirm that that is the logic behind that rule, which I think most people will find quite far secure? Yes, look, as I said, we are bringing forward the social housing package in the very near future, and part of that will be discussion around this recommendation in the scheme. I have discussed with some of your colleagues, and we can discuss it further, I mean we have had this conversation about what people wanted this, and the sense was that people wanted a method of dealing with that €15,000 income. But just to clarify why it is there, it is in order to ensure, and it is not a madcap idea, there was a logic to it, because there was quite a long history with tenant purchase schemes, and in some cases people have not been able to afford to maintain the house thereafter. So in order to ensure the sustainability of the scheme, it is essential that an applicant's income will have a long-term and sustainable nature. This is necessary to ensure that the tenant purchasing the house is in a financial position, as the owner to maintain and ensure the property for the duration of the charge period, in compliance with the conditions of the order of transferring the ownership. A condition of the transfer of ownership of the house is that the tenant purchaser for the duration of the incremental purchase charge, because again that goes on for 20 or 30 years as well, must keep the house in good repair and condition, and maintain house insurance on the property. The tenant purchaser will also be responsible for the normal changes associated with homeowner ownership. The history of it and the research shows that that did not always happen without that income barrier. So to be fair, it is probably recognised that the €15,000 might not be the best way to achieve that, because it does prevent somebody that might have won the lotto, or had a settlement of some sort, that they could actually buy other houses as well. So we are trying to find ways to deal with that, and that will come forward as part of the package as well. But to be clear too, there is probably an impression given that that is the reason people are not buying houses. If you take a sample year, one of the years looked at, over 2,400 applications were made. Less than a quarter were refused to do with the eligibility criteria. It did not affect the other 75%. So just to be clear on that, it is not the big, big issue. Yes, it is an issue for some of us individual cases around the country, but it is not the main one that is the reason people are not using this scheme. Thank you.
Thank you for downloading 🙏
If you publish this material on social media, we would be very grateful if you tagged VideoParliament. It helps us reach more people and keep building a transparent archive of Irish politics.