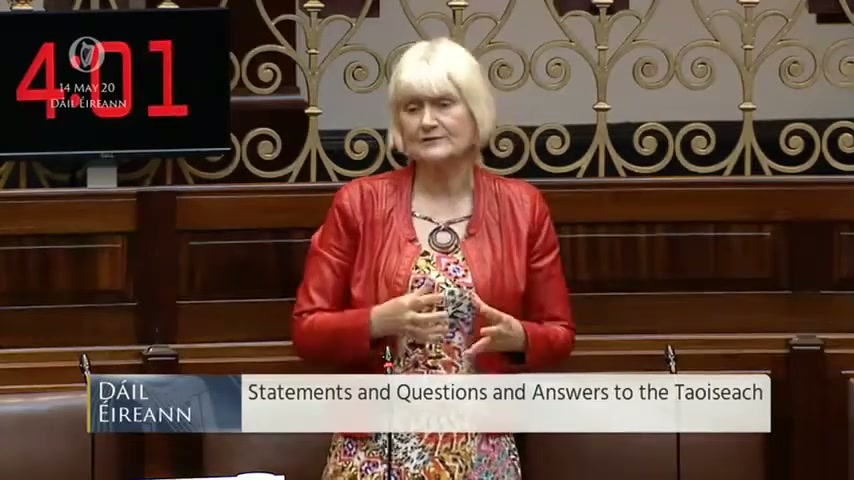
Marian Harkin presses for cash grants to stop business debt
Marian Harkin challenged the minister on low take-up of liquidity measures and urged direct cash grants to cover ongoing costs so businesses do not restart with increased debt. She said many firms are running out of cash, will reopen at reduced turnover and do not want additional borrowing, and asked whether grants like those in the UK, Germany and Denmark would be provided.
Concerns from businesses
Marian Harkin cited an IBEX survey showing many companies are running out of cash and are reluctant to take on more debt. She highlighted ongoing liabilities such as utility bills, rent and insurance, and warned that the end of lockdown will not mean a return to normal trade for many firms with turnover reduced to 20–50%.
Government supports outlined
The minister set out a suite of supports including loans and grants. The business continuity grant is available via the local enterprise office to help businesses access advice and financial planning, and there are grants for getting online. The minister also announced a €250 million restart grant and said details would be brought to Cabinet tomorrow, with a maximum payment of €10,000 linked to last year’s rates and intended as a direct cash injection to cover costs incurred while closed.
Wage support and loan terms
The minister reminded the House that the wage subsidy scheme will continue until 16 June, subsidising up to 85% of wages to a maximum of €410 per worker. On borrowing, the minister said Microfinance Ireland COVID-19 loans carry rates of 4.5%–5.5% with six months interest-and-repayment-free (an effective annual rate of just over 3%), SBCI COVID-19 working capital loans are offered at a maximum of 4%, and the Future Growth Loan scheme has a maximum rate of 4.5% for loans under £250,000. He also said the government is exploring measures to reduce interest rates further, including changes to Microfinance Ireland funding and a new £2 billion credit guarantee scheme with an 80% state guarantee to support below-market rates.
We publish thousands of recordings to make Irish politics transparent and resistant to manipulation. Spotted an error? Report it — together we are building a reliable archive of Irish politics.
So good, they named it twice, Cathaoirle. Anyway, Minister, according to an extensive IBEX survey, many businesses are running out of cash, and yet the take-up of some of the liquidity measures announced by your department is low. So why is this happening? Well, one of the reasons is that many companies don't want to add to their increasing levels of debt. I've spoken about this before, their utility bills, their rent, their insurance. And I think we also have to remember that an end to lockdown is not the start of normal trade. Many businesses will have turnovers from around 20, or at best 50%, so they have no profit. So they don't want to restart with an overhang of debt. So my question to you is, will you give cash grants to businesses like in the UK, Germany, Denmark, to specifically cover ongoing costs when closed, so that they're not restarting with a significant overhang of debt? Thank you. Thank you, Deputy, for raising that. And we currently have a suite of supports. Some of them are loans, and some of them are grants. Now, we have the business continuity grant. You get that from the local enterprise office. So that gives you access to somebody to give you advice and to help you put together a financial plan for your company. So that's available. Then we have the grants for getting online. And in fairness, a lot of businesses have taken that up as well. And then finally, we have the restart grant. And the restart grant is a fund that I announced last Saturday week of €250 million. And tomorrow I bring to Cabinet the details of how that loan or how that grant will work. So it's going to be a maximum of 10,000 euros. And it will be connected to the rates that businesses paid last year. And that would be a direct cash grant into their business. And that means that to be able to use that money, whether they need to buy some pair specs or whatever to put up PPE protections in their businesses, they can use it for overhanging costs. Maybe they have the ESB bill and a few other things like that. So it's there for them to use. And I think it will be very much welcomed. And then, of course, there's the wage subsidy scheme. And I think that people should remember that this scheme, when you start to bring your workers back, they'll all be coming back hopefully over the next period of time. So the wage subsidy scheme means that your wages will be paid. If you're an employer, the state will pay the wages of your workers up to 85%, a maximum of €410 per worker. And that will continue until the 16th of June. So that in itself, when you have your business back up and running, will actually be a cash injection as well. Thank you. I'm happy to hear that the restart grant can be used to specifically cover costs that have occurred when the business was closed. My second question is on borrowing. I've spoken about this before, the rates. Government can borrow less than 1%, yet we're charging 4% to 5% over the lifetime of the loan. And my question is, why are we so out of kilter with our European partners? What is the reason for this? Is it to protect our banks and their profitability? Thank you, Minister. Well, interest rates under the microfinance Ireland COVID-19 loan schemes have been reduced down to between 4.5% and 5.5%. The first six months are interest and repayment free, which means there's an effective annual interest rate of just over 3%. Under the SBCI COVID-19 working capital scheme, loans are offered at a maximum rate of 4%. And this represents a significant saving compared to other similar lending products in the market. And under the Future Growth Loan scheme, the maximum interest rate is 4.5% for loans less than £250,000. And can I just say that we are exploring measures to further reduce interest rates. And I continue to look at whatever opportunities there are for lower interest rates on loans. For example, in relation to Microfinance Ireland, a recently secured government approval to amend the process by which Microfinance Ireland is funded, so that they can access cheaper funding once the necessary legislation is in place. That will support further lending by Microfinance Ireland at heavily subsidised interest rates. And under the new £2 billion credit guarantee scheme, interest rates will be below market rates because the State is guaranteeing 80% of those loans. powerppo Sorry.
Thank you for downloading 🙏
If you publish this material on social media, we would be very grateful if you tagged VideoParliament. It helps us reach more people and keep building a transparent archive of Irish politics.